Non-resident buyers can usually secure mortgage finance on the French Riviera and in Ibiza, but the terms are conditional, not automatic. Expect a bigger deposit than a resident would pay, a hard cap on how much of your income can go towards repayments, mandatory borrower insurance and a properly drafted finance clause protecting your deposit if the loan falls through. Get those three right before you sign anything, and the rest of the process is manageable.
TL;DR:
- Non-resident buyers should prepare for a larger deposit, usually 50 to 70% LTV, and plan for additional costs like transfer taxes and borrower insurance.
- The financing process involves a series of steps, including a formal mortgage application, binding loan offers, and legal registration, with deadlines typically around 45 to 60 days.
- A well-drafted finance clause is crucial for recovering deposits if the loan is refused, especially for cross-border applications that take longer to process.
- Refinancing in France or Ibiza depends on interest rate changes and improved financial situations, but switching lenders often incurs significant registration and exit costs.
- Working with a buyer agent can streamline coordination between property search, financing, and legal timelines, reducing the risk of costly mistakes or missed deadlines.
Table of Contents
- What real estate debt financing includes for Riviera and Ibiza buyers
- What LTV and deposit should you expect as a non-resident?
- How does the financing timeline actually work?
- What costs sit beyond the deposit?
- How do lenders assess non-resident applications?
- How can you strengthen your application before applying?
- How Living On The Cote d’Azur supports financed purchases
- What refinancing options exist once you’ve completed?
- Where financing plans usually go wrong
- Let Living On The Cote d’Azur coordinate your purchase and financing
- Sources
- FAQ
What real estate debt financing includes for Riviera and Ibiza buyers
For this article, real estate debt financing means mortgages, bridging loans, and lender guarantees used by private individuals buying a home, second residence, or small investment property. It does not cover institutional lending to developers or large-scale debt funds, which is a separate world with different rules entirely.
In France, a loan is formalised through the acte de crédit, a notarial deed the notaire prepares alongside the property deed itself. Spain works differently: your Ibiza lender issues a binding FEIN (a standardised European information sheet) followed by an oferta vinculante, both of which set out the exact terms before you commit.
Common product shapes for international buyers include fixed-rate amortising loans (the default for most French banks), private banking arrangements for larger purchases, and mortgages backed by a mutual guarantee society rather than a mortgage registration. Each carries different costs and flexibility, which matters more than it first appears once you start comparing offers.
What LTV and deposit should you expect as a non-resident?
Your nationality, tax residency, and how you plan to use the property all shape the deposit a bank will ask for.
Non-EU buyers, including Americans, Brits post-Brexit, and buyers from further afield, generally see LTVs closer to 50 to 70%, sometimes lower for complex income structures like foreign trusts, multiple business entities, or irregular self-employed earnings. Banks want to see the money trail clearly, and anything opaque gets a more conservative offer.
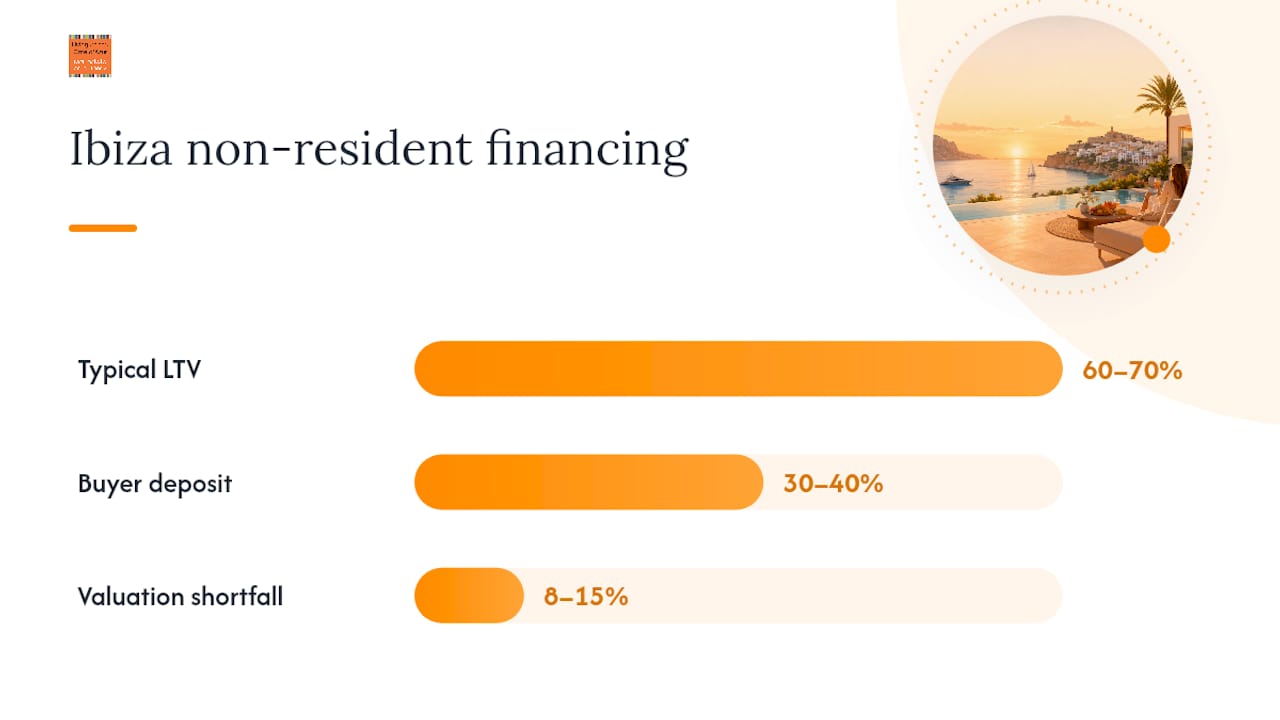
Second homes and buy-to-let purchases attract tighter scrutiny than a primary residence would, even for EU nationals. On Ibiza specifically, non-resident LTV typically sits at 60 to 70%, and bank valuations frequently come in 8 to 15% below the price you negotiated with the seller. That gap has caught out more than one buyer at completion, so plan your cash reserve with that shortfall already baked in rather than hoping the appraisal matches your offer.
How does the financing timeline actually work?
The process follows a fairly fixed sequence, and understanding where the legal protections sit in that sequence matters more than the individual steps themselves.
- Agreement in principle. A broker or bank gives an informal assessment of what you could borrow, based on income and existing debts.
- Compromis de vente with a finance clause. You sign the preliminary contract, and the condition suspensive de financement gives you roughly 45 days to secure a loan. If the bank refuses, you can walk away and recover your deposit, provided the clause was drafted correctly and you applied within the agreed terms.
- Full mortgage application. Full documentation goes to the lender for formal underwriting.
- Offre de prêt. The bank’s binding offer arrives, followed by a mandatory 10-day reflection period during which you cannot accept it, even if you want to move faster.
- Acte de crédit and completion. The notaire finalises the loan deed alongside the sale and registers the lender’s security.
For non-resident files, ask your notaire or broker for a 60-day finance clause rather than the standard 45. Cross-border paperwork, translated documents, and foreign bank verification routinely take longer than domestic files, and a tight deadline puts unnecessary pressure on everyone involved.
What costs sit beyond the deposit?
Banks will not finance every cost attached to a purchase, and buyers who forget this often find themselves short of cash at exactly the wrong moment. Budget for these separately from your deposit:
- Notaire fees and transfer taxes, typically 7 to 8% of the price on resale property in France, but only 2 to 3% on new-build.
- Borrower insurance (assurance emprunteur), which is effectively compulsory and counts towards your affordability calculation.
- Guarantee or caution costs, charged instead of a mortgage registration by some lenders.
- Bank arrangement fees and valuation fees, usually a few hundred to a couple of thousand euros depending on loan size.
- Early repayment penalties and mainlevée costs if you sell or refinance before the loan term ends.
Add ongoing property taxes into your long-term affordability picture too. They will not appear on your mortgage statement, but they shape what you can genuinely afford to hold each year.
How do lenders assess non-resident applications?
French banks apply a debt-to-income ceiling under HCSF rules: your total loan repayments, including borrower insurance, generally cannot exceed 35% of net household income. The typical maximum term is 25 years, occasionally stretched to 27 for select new-build purchases.
Your document pack should be ready before you start seriously viewing property, not after you’ve found something you love:
- Passports and proof of tax residency
- Two to three years of tax returns
- Recent payslips or certified accounts if self-employed
- Three to six months of bank statements
- Proof of the source of your deposit funds
- The draft compromis once you have one
US citizens face extra scrutiny too, given FATCA reporting obligations that some French banks are reluctant to take on at all.
How can you strengthen your application before applying?
A specialist mortgage broker earns their fee by knowing which banks actively want non-resident or complex-income files, rather than sending you through a generic branch process where nobody has the authority to say yes. A well-packaged file paired with an early agreement-in-principle materially improves approval odds, and brokers who work this market daily know exactly which documents each lender will ask for twice.
Open a French bank account as early as you can, and get certified translations of your income documents sorted well before your finance clause deadline starts ticking. Since the loi Lemoine reform, borrowers can shop for external borrower insurance independently, which often lowers your monthly cost and improves your debt ratio in the same move.
Pro Tip: *If you’re transferring a large deposit from outside the eurozone, ask your broker about locking an exchange rate a few weeks ahead of completion.
How Living On The Cote d’Azur supports financed purchases
A buyer agent’s real value in a financed purchase is timing coordination, something banks and sellers rarely think about from your side of the table. A buyer agent can help align the finance clause deadline with realistic broker and bank timelines, introduce clients to trusted mortgage brokers and bilingual notaires, and help prevent the compromis negotiation from moving faster than the financing process.
The right moment to bring in a buyer agent for financing support is before you make an offer, not after. Once a compromis is signed with a finance clause that’s too tight, your options narrow fast, and renegotiating deadlines with a seller rarely goes smoothly.
What refinancing options exist once you’ve completed?
Refinancing a French or Spanish mortgage works differently depending on which side of the border your property sits, and the conditions attached matter as much as the headline rate.
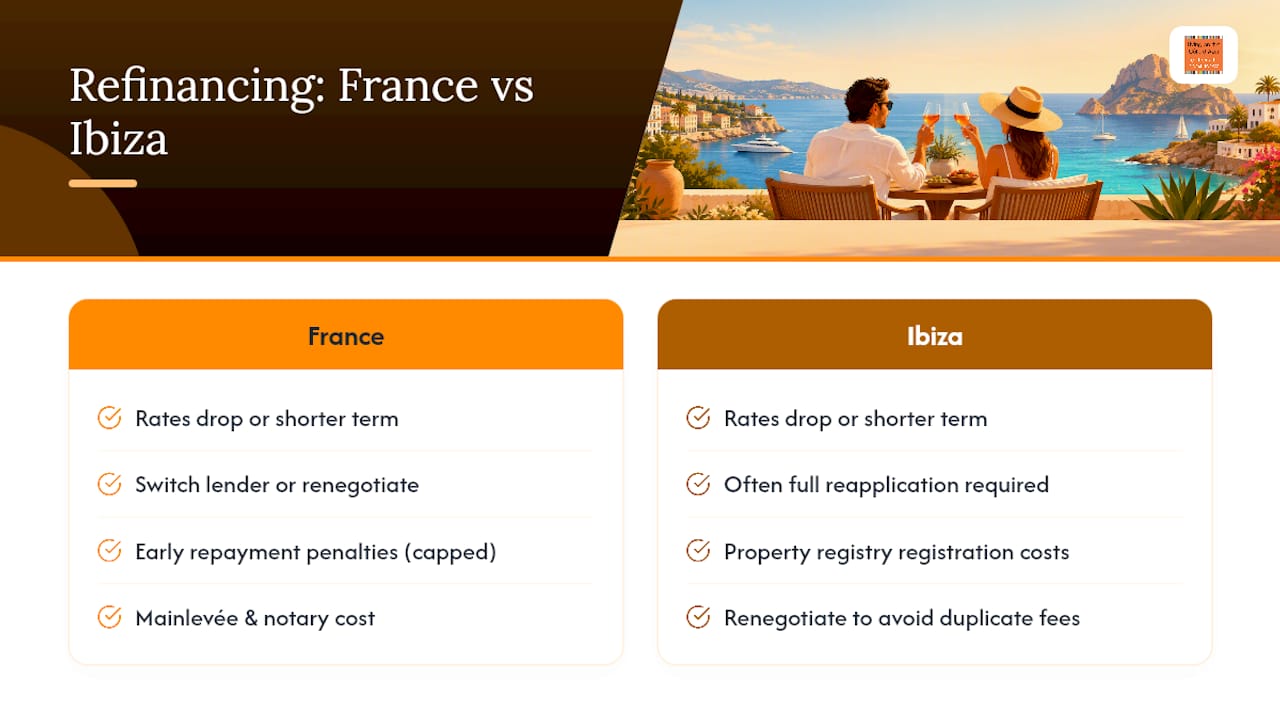
In France, refinancing (renegotiating your existing loan or switching lender entirely) becomes worthwhile mainly when rates have dropped meaningfully since you signed, or when your financial situation has improved enough to justify a shorter term. Early repayment penalties apply if you switch lenders, typically capped by law, but still worth calculating against your projected savings before committing. A mainlevée releases the original lender’s security once the old loan is settled, and that step carries its own notarial cost.
If your rental income or salary has shifted since purchase, that reassessment can go either way.
On Ibiza, refinancing through a Spanish lender generally requires a similar full reapplication, and switching from one bank to another involves its own registration costs at the property registry. Some buyers instead choose to renegotiate terms with their existing lender rather than switch entirely, since it avoids duplicating registration fees. Whichever route you take, get a written comparison of total costs, not just the new interest rate, before signing anything. A lower rate with high switching costs can easily cost more over five years than staying put.
Where financing plans usually go wrong
The mistakes I see repeated most often aren’t about interest rates. They’re about sequencing.
If you take one thing from this article, make it this: secure a genuine agreement-in-principle and a realistic finance clause before you make a binding offer on anything. Everything else in the process becomes far easier to manage once that foundation is solid.
— Ab Kuijer
Let Living On The Cote d’Azur coordinate your purchase and financing
Working through non-resident mortgage rules, notaire timelines, and bank documentation while you’re based outside France or Spain is genuinely hard to do alone, and most buyers only discover the gaps once a deadline is already looming. An independent buyer agent can be an alternative to going through this process solo or relying on a single local agent’s limited network by searching the entire market through local agents and developers, introducing clients to trusted mortgage brokers and bilingual notaires, and helping keep the finance clause deadline realistic given broker capacities.
The firm’s search mandate service runs your property search while coordinating with the financing side in parallel, so viewing, negotiating, and applying for your mortgage happen on a realistic shared timeline rather than in isolation. If you’re planning a financed purchase on the Riviera or in Ibiza, get in touch with Living On The Cote d’Azur to talk through your situation before you make an offer.
Sources
- Service-public.fr — Condition suspensive de financement
- FrenchNotaires — French mortgage non-resident buyer (2026)
- Optimavi — Buying property in France (2026)
- Qoridor — French mortgage guide 2026
- Buvivo — Buying property in Ibiza and Formentera (2026)
FAQ
Can non-residents get a mortgage on the French Riviera?
Yes, French banks routinely lend to non-residents, though affordability checks and deposit requirements are stricter than for residents. Expect a larger deposit and closer scrutiny of your income sources and currency exposure.
What is the HCSF 35% rule?
It’s a debt-to-income cap requiring that your total loan repayments, including borrower insurance, generally stay under 35% of net household income. French banks apply this uniformly to residents and non-residents alike.
Why does the finance clause matter so much?
The condition suspensive de financement lets you cancel the compromis and recover your deposit if your loan is refused, provided it’s drafted correctly and you apply within the agreed window. Without it, a refused loan could mean losing your deposit entirely.
How much deposit should I plan for in Ibiza?
Non-resident LTV on Ibiza typically runs 60 to 70%, so plan a deposit according to LTV expectations plus a buffer for valuations that often come in below the agreed price. Purchases over €2m sometimes access better terms through private banking.
Can a buyer agent help with mortgage financing?
Yes. Living On The Cote d’Azur coordinates finance clause deadlines with your mortgage broker’s timeline and introduces clients to trusted brokers and bilingual notaires as part of its buyer agent services, reducing the risk of a mismatch between your offer and your financing.
Recommended
 //