VEFA is France’s legally regulated off-plan sale, and it protects you with staged payments and a mandatory completion guarantee. Before you commit any money, confirm the guarantee is extrinsic and have a bilingual notary review the reservation pack. Get those two things right, and buying a new home on the Riviera before it’s even built stops feeling like a leap of faith.
TL;DR:
- Buyers should verify that the completion guarantee is extrinsic and obtain the guarantor’s attestation before signing the reservation contract.
- The deposit is limited to 5%, 2%, or none depending on the time remaining before deed signing, and must be held in a sequestered account.
- Payments are legally capped at roughly one-third, two-thirds, and full payment during construction, with the final balance due on delivery.
- The notary checks the land title, planning permissions, and GFA validity before finalizing ownership transfer.
- The delivery process includes a detailed property inspection, a formal handover record, and a one-month window to report defects.
Table of Contents
- What is VEFA and how ownership transfers during construction
- Reservation contract: mandatory contents, deposit limits and the ten-day withdrawal right
- Staged payments: the legal schedule, how calls work and what to watch for
- Guarantees and warranties: GFA, refund guarantees and the post-delivery regimes
- The notary and the final deed: what gets checked and how remote signing works
- Delivery, snagging and warranties: accepting or refusing handover correctly
- Financing VEFA as a non-resident: lender practicalities and timing
- Practical checklist for international buyers before signing anything
- Due diligence on the developer and the planning permissions before you sign
- Tax implications and fees for international buyers under VEFA
- Main risks in VEFA transactions and how to manage them
- Changes and cancellations after signing the reservation contract
- What overseas buyers underestimate about buying off-plan in France
- How Living on the Côte d’Azur supports VEFA purchases
- Primary sources and recommended further reading
- Sources
- FAQ
What is VEFA and how ownership transfers during construction
VEFA stands for “vente en l’état futur d’achèvement”, which translates roughly as “sale in a future state of completion”. It’s a sale contract defined in the Construction and Housing Code, and it governs almost every new-build apartment and villa sold on the French Riviera before the last coat of paint goes on.
Here’s the part that surprises a lot of overseas buyers: you don’t wait until the building is finished to become an owner. Ownership transfers progressively, in step with construction, rather than in one single handover at the end.
- You become owner of the existing structure the moment you sign the notarial deed, even if that’s just foundations at the time.
- As each stage is built, ownership of that stage automatically becomes yours, without a new deed for every phase.
- The developer keeps control of the building site and remains responsible for completing the works until delivery.
This staged model is precisely why French law wraps VEFA in extra protections. You’re paying for something that doesn’t fully exist yet, so the rules exist to make sure your money and your legal position are both secured along the way.
Reservation contract: mandatory contents, deposit limits and the ten-day withdrawal right
Before any notarial deed, you sign a “contrat de réservation”, the reservation contract. This is the document that locks in the terms, and French law is specific about what it must contain.
- Precise identification of the lot: the apartment or villa number, floor, approximate surface area and layout.
- The notice descriptive: a technical description of materials, finishes and shared facilities, which carries real legal weight, unlike a glossy brochure.
- The provisional price and how it may be revised.
- A maximum date by which the notarial deed must be signed.
- An indicative delivery timetable for the works.
- A financing clause, if your purchase depends on a mortgage, so you can withdraw without penalty if the loan is refused.
- The deposit amount, which is capped by law depending on how far away the deed signing is: 5% if signature is due within a year, 2% if within one to two years, and nothing at all if completion is more than two years out.
That deposit cannot sit in the developer’s current account. It must be held in a sequestered account, typically with the notary, until the sale is finalised. Once you’ve signed, you get a ten-day cooling-off period that starts the day after you personally receive the contract or it’s first delivered by registered post. Within that window you can walk away for any reason and without penalty, by sending a registered letter with acknowledgement of receipt (a “lettre RAR”). If the tenth day falls on a weekend or public holiday, the deadline simply rolls to the next working day.
Staged payments: the legal schedule, how calls work and what to watch for
Once the cooling-off period passes and you’ve signed the deed, payments follow a legally fixed schedule tied to construction progress, not to the developer’s cash flow needs. According to Zimo’s breakdown of VEFA mechanics, the cumulative ceilings are set by law and cannot be exceeded at any stage.
- Up to around one-third of the price once the foundations are complete.
- Up to about two-thirds once the building reaches “hors d’eau”, meaning watertight, typically walls and roof in place.
- Up to nearly all (just short of full payment) once the works are fully complete.
- The final small balance only on delivery, once you’ve accepted the property.
Developers are free to split these into smaller instalments tied to intermediate milestones, but the cumulative total at each stage can never go above those caps. If defects appear at handover, you can withhold that last slice until they’re fixed. For non-resident buyers coordinating a mortgage from abroad, this schedule also determines when your lender needs to release funds, and it’s worth asking your bank early how it handles interim interest on drawn-down but unused capital.
Guarantees and warranties: GFA, refund guarantees and the post-delivery regimes
The single most important document in a VEFA file is the “garantie financière d’achèvement”, or GFA, the completion guarantee. Since a reform in 2015, developers selling under VEFA must provide this guarantee, and according to Actes Alliances Notaires’ guide to buying off-plan in France, it’s normally extrinsic, meaning it comes from a bank or an insurer rather than from the developer’s own balance sheet.
- An extrinsic guarantee means an outside financial institution commits to funding completion if the developer fails, which is the standard buyers should insist on.
- An intrinsic guarantee, where the developer effectively self-certifies using pre-sale levels, offers weaker protection and is far less common today.
- A refund guarantee is a related but different promise: it covers giving your money back if the project is abandoned, rather than guaranteeing the building gets finished.
Notaries won’t let the acte authentique proceed without checking the GFA, but you shouldn’t wait for the notary to be your only safeguard: ask the developer for the guarantor’s attestation directly and read it before you sign anything.
Pro Tip: Ask specifically whether the GFA is extrinsic, and request the guarantor’s name and attestation as an annex to the reservation file, not just a verbal assurance.
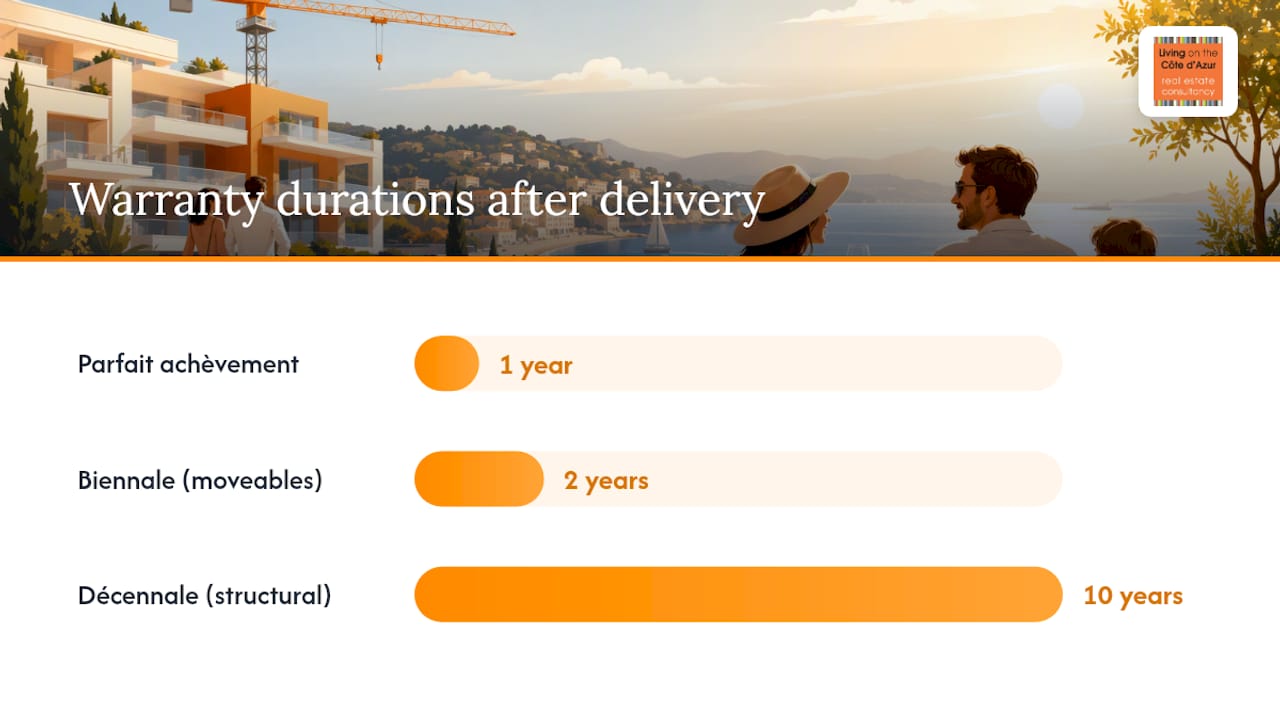
Once you’ve moved in, three warranty regimes protect you. The “garantie de parfait achèvement” covers any defect you report within the first year after delivery. The “garantie biennale” covers moveable fittings such as shutters, boilers and taps for two years. The “garantie décennale” is the big one: ten years of cover for structural defects that affect the building’s soundness or make it unfit for its purpose.
The notary and the final deed: what gets checked and how remote signing works
The notary is not just a formality-signer in a VEFA transaction. Before the acte authentique can be completed, the notary verifies land title and registration, checks planning consents attached to the project, and confirms the GFA is in place and valid, as Actes Alliances Notaires explains.
- Title and registration checks on the land and the development.
- Verification of the extrinsic completion guarantee before the deed is signed.
- Preparation and registration of the acte authentique, which formally transfers ownership of the current construction stage to you.
The gap between reservation and the notarial deed typically runs a few months, giving the notary time to complete these checks and giving you time to arrange financing. If you can’t be in France on signing day, a “procuration”, a power of attorney, lets a representative sign on your behalf. This is standard practice for non-resident buyers, but it needs to be drafted and often notarised or apostilled in advance, so raise it with your notary as early as possible rather than the week before completion.
Delivery, snagging and warranties: accepting or refusing handover correctly
Delivery, or “livraison”, is the moment the developer hands you the keys and you formally take possession. It’s also the moment you can lose leverage if you’re not careful.
- At handover, you and the developer sign a “procès-verbal de livraison”, a formal record of the property’s condition. This is your one real chance to list every defect as a “reserve”.
- Be precise. According to Zimo’s guide to VEFA payment and delivery mechanics, you have one month after delivery to report apparent defects you didn’t catch on the day, so a written follow-up matters if you spot something later.
- You’re entitled to withhold part or all of the final 5% until the reserves listed are properly resolved, which is often the fastest way to get a developer to move.
- The warranty clocks (parfait achèvement, biennale, décennale) all start running from the delivery date, so that date needs to be recorded clearly and shouldn’t be casually agreed to just to close the file.
Accepting delivery without noting a defect can make it harder to claim later, so walk the property slowly and don’t sign anything you haven’t checked room by room.
Financing VEFA as a non-resident: lender practicalities and timing
Financing an off-plan purchase from abroad has its own rhythm, because the bank doesn’t hand you the full loan on day one. Disbursements are staged to match the developer’s calls: foundations, watertight stage, completion and delivery, mirroring the legal payment schedule.
- Lenders typically release funds in tranches that match each construction milestone rather than as a single lump sum.
- Until the full loan is drawn, you may pay interim interest only on the amount actually released, which changes your monthly costs during the build.
- Non-resident borrowers are often asked for a larger equity contribution and more extensive documentation than French residents, though exact requirements vary by bank and by profile.
- If your lender’s disbursement dates lag behind the developer’s payment calls, you can end up needing to bridge the gap yourself, so it’s worth asking your bank to align its schedule with the contract’s milestones before you sign the loan offer.
Coordinating this properly from another country, often across time zones and languages, is one of the more common places where non-resident buyers lose weeks they didn’t expect to lose. Building in a buffer of a few weeks between expected lender release dates and contractual payment deadlines tends to save a lot of stress later.
Practical checklist for international buyers before signing anything
A few checks, done properly before you sign, prevent most of the problems that catch overseas buyers out later.
- Confirm the GFA is extrinsic and get the guarantor’s attestation annexed to the reservation file, not just mentioned in passing.
- Have the notice descriptive translated and reviewed by a notary or bilingual lawyer, since marketing brochures carry no legal weight and only the contract and deed do.
- Check that your deposit will genuinely be sequestered, and that the financing clause matches the loan you’re actually applying for.
- Negotiate the wording on late-delivery penalties and make sure a specific, workable delivery date appears in the acte authentique.
- Arrange your power of attorney and set up currency transfers well ahead of each payment call so the timing lines up with the construction schedule.
Pro Tip: Keep a simple spreadsheet mapping the contract’s payment percentages against your lender’s release dates and your currency transfer plan. It sounds unglamorous, but it’s the single easiest way to catch a mismatch before it becomes a funding gap.
Due diligence on the developer and the planning permissions before you sign
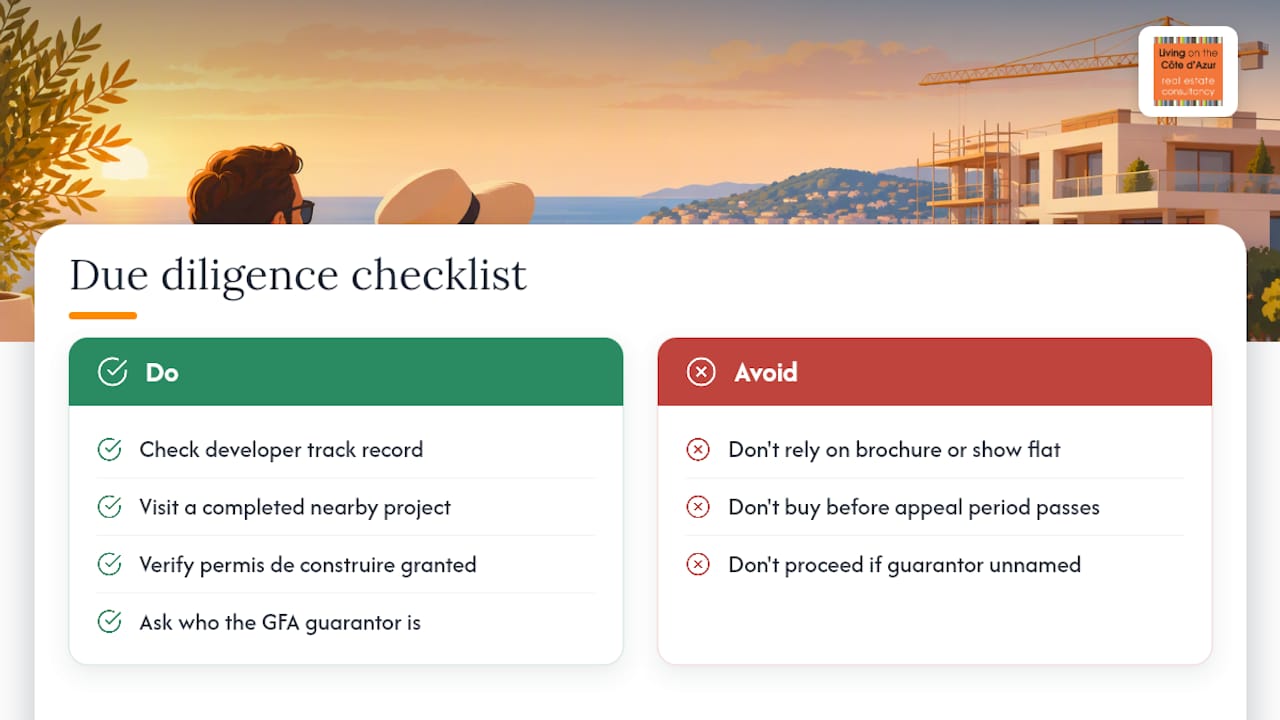
Before you sign the reservation contract, spend time on the developer itself, not just the apartment layout. Ask how long the company has operated in France, look at other completed projects nearby, and if possible visit one. A developer with a track record of finished, well-reviewed projects on the Riviera is a very different proposition from a newly formed entity with a single project on its books.
Check the planning permission, the “permis de construire”, attached to the specific programme. Confirm it has been granted, that any appeal period has passed without challenge, and that the plot’s use matches what’s being sold to you. Planning disputes can delay or derail a project long after you’ve paid your deposit, so this isn’t a box-ticking exercise.
It’s also worth asking who the GFA guarantor is before you commit, rather than after. Banks and insurers don’t issue completion guarantees to just any developer, and the identity of the guarantor tells you something about how the project has been assessed financially. If a developer is vague or reluctant to name the guarantor, treat that as a signal to slow down rather than speed up.
This is exactly the kind of groundwork an experienced buyer agent does as a matter of course, because the difference between a well-run programme and a shaky one is rarely visible in the show flat or the brochure.
Tax implications and fees for international buyers under VEFA
VEFA purchases carry a different fee structure to buying an existing home, and it’s worth understanding before you budget. New-build purchases are typically subject to VAT included in the sale price rather than the transfer taxes applied to older properties, and notary fees on new builds tend to run lower as a proportion of the price than on resales, reflecting the lower registration duties involved.
Beyond the purchase itself, ongoing property taxes such as the “taxe foncière” apply once the property is completed and registered, though new builds can sometimes benefit from a temporary exemption depending on local rules, so it’s worth checking with the notary or local tax office at the time of delivery rather than assuming a blanket rule.
International buyers should also think ahead to structuring: whether to hold the property personally or through a company such as an SCI has consequences for inheritance planning and, for some nationalities, for tax reporting obligations back home. None of this replaces proper advice from a tax specialist familiar with both France and your home country’s rules, particularly since treatment can differ sharply depending on your residency status and nationality. What VEFA doesn’t change is the need for that advice early, ideally before you sign the reservation contract, not after the deed is done.
Main risks in VEFA transactions and how to manage them
The biggest risk in any off-plan purchase is straightforward: the developer fails to finish the building. That’s precisely why the GFA exists, and why confirming it’s extrinsic rather than intrinsic is the single highest-value check you can make.
A second risk is delay. Construction timetables slip, and while the legally binding delivery date sits in the acte authentique, Kohen Avocats notes that late-delivery penalties usually run from that contractual date and are often expressed as a small fraction of the price per day, so precise drafting of that clause matters more than it might seem.
A third risk is the gap between what’s marketed and what’s contractually promised. Renderings and show flats sell a feeling; only the notice descriptive and the deed describe what you’re legally entitled to receive, which is why cross-checking the two documents before signing is worth the time it takes.
Currency risk is a quieter one for non-resident buyers, since staged payments spread your exposure to exchange rate movement across the build period rather than concentrating it in one transfer. Mitigating most of these risks comes down to the same handful of actions: verify the GFA, read the notice descriptive properly, get the delivery date and penalty clause right, and don’t rely on a single point of contact for translation or oversight.
Changes and cancellations after signing the reservation contract
Once the ten-day withdrawal period has passed, cancelling a VEFA reservation becomes more complicated, though not impossible. The financing clause is your main safety net here: if your mortgage application is refused on the terms specified in the contract, you can typically withdraw and recover your deposit, provided you’ve respected the timeframes and conditions written into that clause.
Changes to the specification, layout tweaks or finish upgrades, are usually handled through formal amendments to the reservation contract or through separate “travaux modificatifs acquéreur” agreements, which carry their own costs and paperwork. Verbal promises from a sales agent about a change to the notice descriptive mean nothing until they’re written into the file.
If a developer wants to modify a major term, such as a significant delay to the delivery date or a change in specification, you generally have grounds to query or reject the change rather than accept it silently. Disputes at this stage are one of the more common reasons overseas buyers end up needing a bilingual lawyer partway through a purchase they thought was straightforward, which is exactly the kind of complication worth anticipating rather than discovering.
What overseas buyers underestimate about buying off-plan in France
The gap I see most often isn’t in the law itself, it’s in the assumption that the show flat and the sales brochure describe what you’re actually buying. They don’t. Only the reservation contract, the notice descriptive and the final deed carry legal weight, and a beautifully rendered kitchen means nothing if the notice descriptive says something different.
The second underestimated thing is how much coordination a VEFA purchase demands across time zones: vetting the developer, checking the GFA, aligning lender drawdowns with payment calls, arranging a power of attorney, all while living several thousand kilometres from the building site. An independent buyer agent who does this daily, rather than once every few years as most buyers do, tends to catch the small mismatches before they become expensive ones.
— Ab Kuijer
How Living on the Côte d’Azur supports VEFA purchases
Buying off-plan on the Riviera works best when someone is checking the contract, the guarantee and the timeline on your behalf, not just showing you floor plans. An independent buyer agent represents buyers only, searching new-build and off-market stock across the entire local market through a network of agents and developers, then coordinating contract review, the GFA check and the notarial process with bilingual experts.
If you’re considering a VEFA purchase on the French Riviera, our Buyer Agent service is the natural starting point: get in touch and we’ll walk through your search and the contract protections together.
Primary sources and recommended further reading
Verify the cooling-off rules directly via Service-public’s guidance on VEFA reservation contracts, and for a fuller legal walkthrough aimed at foreign buyers, see Kohen Avocats’ guide to buying off-plan in France.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- Service-public: information on reservation contract and cooling-off rights (VEFA)
- Zimo: VEFA mechanics, guarantees and payment calendar
- Maître Reda Kohen: Legal guide for foreign buyers on VEFA
- Actes Alliances Notaires: buying off-plan (VEFA) guide
FAQ
What is the 5/7 rule in France?
There is no established “5/7 rule” tied to VEFA or French property law; this appears to be a confusion with unrelated regulations. What matters for VEFA specifically are the deposit caps of 5%, 2% or none depending on how far away the deed signing falls, and the staged payment ceilings of 35%, 70% and 95%.
Am I a first-time buyer if I’ve owned property abroad?
French VEFA rules themselves don’t hinge on “first-time buyer” status; the legal protections, deposit caps and payment schedule apply the same way regardless of your property history. First-time buyer status matters mainly for certain tax reliefs in some countries, so check that definition with a tax adviser in your home jurisdiction rather than assuming it carries over to France.
What are the disadvantages of buying property in France as a foreigner?
The main challenges are practical rather than legal: coordinating translations of technical documents like the notice descriptive, arranging financing and power of attorney from abroad, and managing snagging and handover without being on site. None of these are barriers, but they do mean overseas buyers often lean on a bilingual notary or a buyer agent to keep the process moving smoothly.
What does VEFA mean?
VEFA stands for “vente en l’état futur d’achèvement”, meaning a sale of a property in its future state of completion. In practice, it means you buy a home before it’s finished, with ownership transferring in stages as construction progresses and payments capped by law at each milestone.
Recommended
 //