The French Riviera can become a genuine generational legacy asset because it combines three things that rarely sit together: a location that cannot be replicated, a property market that has shown real resilience through recent cycles, and legal structures that, handled properly, let families pass a home down rather than lose it to taxes or disputes. Families can turn a single villa into a multi-generational anchor, but poor planning can cause others to lose that chance.
TL;DR:
- French Riviera properties benefit from strict supply limits and preservation laws that protect their rarity and long-term value.
- Recent data shows prices have remained stable or increased slightly despite falling transaction volumes, driven mainly by cash-rich, long-term buyers.
- Legally, structuring ownership through a SCI and addressing French inheritance rules are crucial for maintaining family control and avoiding forced sales.
- Proper family governance, including written decision protocols and regular meetings, significantly improves the likelihood of preserving a property across generations.
- Securing and maintaining a legacy property requires thorough due diligence, off-market searches, strategic planning, and ongoing stewardship beyond initial purchase.
Table of Contents
- What makes the French Riviera irreplaceable as a legacy location
- Market resilience: what recent data tells long-term holders
- How Riviera property fits into a family’s wider portfolio
- Ownership and inheritance: what French law means for your legacy
- Family governance: how to keep a property in the family
- How to secure and protect a Riviera legacy property
- A buyer agent’s view on when the Riviera is the right legacy play
- How we help you build a Riviera legacy, not just buy a house
- FAQ
- Sources
What makes the French Riviera irreplaceable as a legacy location
Some assets hold value because supply simply cannot expand to meet demand, and the Riviera is a textbook case. The coastline between Menton and Saint-Tropez offers a Mediterranean climate, direct access to Nice Côte d’Azur airport, and a density of cultural institutions, from the Matisse museums to the Cannes Film Festival circuit, that no newly built resort town can manufacture in a generation.
A handful of features tend to separate a legacy property from an ordinary holiday home:
- Architectural provenance: a Belle Époque villa or a historic Provençal mas carries a story and a rarity that new builds cannot replicate.
- Protected coastline and hillside positions: limited buildable land in prime communes keeps truly exceptional plots scarce.
- Neighbourhood hierarchy: areas such as Cap d’Antibes, Villefranche-sur-Mer, Saint-Tropez and the hills above Mougins have sustained outsized prestige for decades.
Older coastal properties also carry conservation duties, from respecting heritage facades to managing erosion risk, which buyers should treat as part of ownership rather than an afterthought.
Pro Tip: Ask any agent for the property’s planning history before falling for the view, since a restricted building envelope is often what protects your future resale value.
Market resilience: what recent data tells long-term holders
Prices on the Riviera do not move in a straight line, but recent figures suggest the market absorbs shocks better than headlines sometimes imply. Analysis from the Chambre des notaires covering the Alpes-Maritimes shows that while transaction volumes have fallen sharply over recent years, prices in several submarkets have continued to hold or show modest increases.
Prices resisting a volume downturn is the pattern worth remembering: fewer sales are closing, yet sellers in sought-after pockets of the Riviera are not being forced to discount, according to the notaires’ own figures.
- Buyers today more often arrive with substantial equity or cash, which tends to reduce exposure to mortgage rate swings.
- First-time buyers form a smaller portion of transactions than in previous cycles, concentrating demand among wealthier, long-term purchasers.
That buyer profile matters for anyone thinking in decades rather than quarters: a market led by cash-rich, patient buyers tends to correct more gently than one driven by leveraged speculation. Treat any single year’s figures as one data point in a longer cycle rather than a verdict on the region.
How Riviera property fits into a family’s wider portfolio
A legacy property earns its place in a portfolio differently from a pure investment. Four key aspects usually apply:
- Appreciation in scarce coastal locations, supported by structural supply limits as noted above.
- Leverage, where financing part of the purchase can enhance returns on equity, when managed prudently.
- Debt pay-down, steadily converting mortgage payments into family equity.
- Currency and residency diversification, valued by many international buyers for spreading risk beyond a single home market through holding a euro-denominated asset in Europe.
The trade-off is liquidity. A family that is property-rich but cash-poor can find itself unable to cover a tax bill or a renovation without selling in a hurry. Addressing that early, through a modest refinance, a partial sale of a secondary unit, or a credit line secured against the property, keeps the asset working for the family instead of against it.
Pro Tip: When a property’s appeal rests mainly on rarity and setting rather than rental yield, weight your decision toward those legacy characteristics and plan your cash reserves accordingly, rather than judging the purchase on annual return alone.
Ownership and inheritance: what French law means for your legacy
French succession law applies forced heirship, which reserves a fixed share of an estate for children regardless of what a will says. For foreign families used to freely disposing of assets by will, this single fact changes how a Riviera property should be structured from day one, as we set out in our guide to forced heirship on the Côte d’Azur.
Many international buyers use a Société Civile Immobilière, or SCI, to hold the property. Shares in the company, rather than the property itself, pass to heirs, which gives a family more control over succession and can simplify gradual transfers of ownership during a parent’s lifetime.
Before any purchase completes, a few items deserve the notaire’s full attention:
- Title history and any servitudes or rights of way affecting the plot.
- Encumbrances, mortgages or unresolved boundary disputes.
- Energy performance obligations, which increasingly affect renovation budgets and resale value.
| Planning step | Why it matters |
|---|---|
| Forced heirship review | Determines the minimum share reserved for children under French law |
| SCI or holding structure | Separates legal ownership from the underlying property for succession purposes |
| Tax and liquidity reserve | Covers inheritance tax exposure and avoids a forced sale |
Specialist guidance from estate planning practitioners, such as JM Clark’s analysis of generational real estate transfer, emphasises that illiquidity and low cost basis make formal structuring essential rather than optional for high-net-worth families. Our own guide to safeguarding a Côte d’Azur legacy explores these aspects in more detail.
Family governance: how to keep a property in the family
Most legacy properties are not lost to market downturns. They are lost to family disagreement, usually because nobody wrote down who decides what. Informal arrangements work fine for one generation and then collapse once cousins, in-laws and differing financial needs to enter the picture.
Three tools reduce that risk — including linking family constitutions to trusts through family governance for HNW in Singapore:
- A written family constitution setting out how decisions on sale, rental or renovation get made.
- A formal operating agreement for any SCI or holding company, defining voting rights and buyout terms.
- Scheduled family meetings, ideally annual, paired with a short mission statement explaining why the property matters to the family.
Practitioners who specialise in generational wealth transfer consistently find that stewardship and governance matter more than price appreciation alone in determining whether a family keeps a property across generations, according to JM Clark’s estate planning research.
Pro Tip: Fund a dedicated maintenance and tax reserve at the point of purchase, since a cash shortfall is the single most common reason families are forced into an unwanted sale.
How to secure and protect a Riviera legacy property
Turning intent into a protected legacy asset starts with due diligence that goes well beyond a pleasant viewing. Before any offer, a thorough review should cover the title chain, servitudes, renovation risk on older structures, and current energy compliance obligations, alongside a frank conversation about ongoing upkeep costs for a historic property near the coast.
This is where working through the entire market, rather than one agency’s own listings, changes outcomes. Searching the full Riviera market through a network of local agents and developers can give access to off-market opportunities that never reach a public portal, as explained in detail in the step-by-step luxury investment guide.
A legacy property is not secured at the signing table. It is secured by the decade of decisions that follow it: maintenance, succession planning and the willingness to treat the house as a shared responsibility rather than a single owner’s asset.
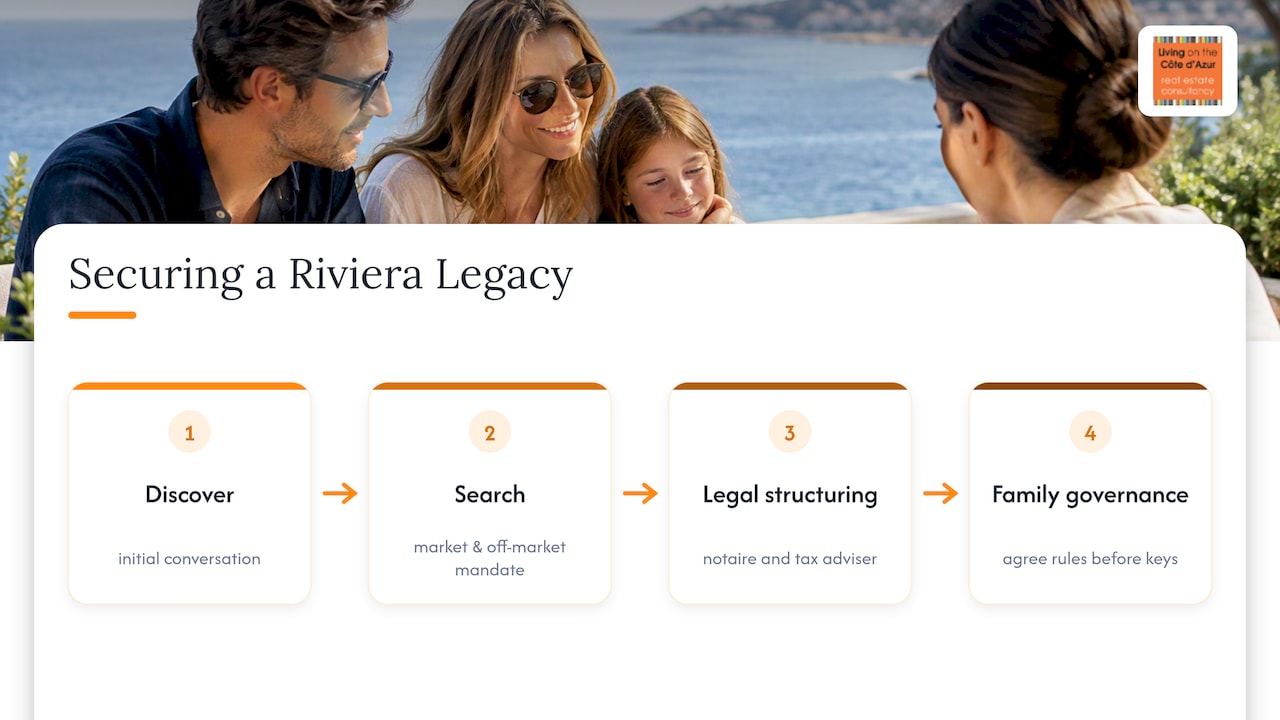
After completion, stewardship becomes the real work: setting aside reserves, choosing renovation specialists who respect the building’s character, and agreeing clear rules if the property will ever be rented out. A practical path typically runs: an initial discovery conversation, a search mandate once criteria are set, legal structuring with a notaire and tax adviser, and a family governance session before the keys change hands. Our own buying guide for securing a Riviera legacy sets out each stage in order.
A buyer agent’s view on when the Riviera is the right legacy play
We recommend the Riviera as a legacy asset when a family has a genuine long horizon, appetite for stewardship, and governance already taking shape, not when someone simply wants a holiday base. We have seen second-home buyers become three-generation stewards once they put a constitution and a reserve fund in place early, and we have seen beautiful villas sold off within a decade when nobody did.
— Ab Kuijer
How we help you build a Riviera legacy, not just buy a house
Finding the right legacy property on the Riviera means searching further than any single agency’s own portfolio. Buyer agents working on behalf of buyers often search the entire market through networks of local agents, developers and off-market contacts, with access to a wide range of properties from Nice apartments to historic villas in Saint-Tropez, Cap d’Antibes and the hills above Monaco.
We coordinate the parts that matter most for a legacy purchase: comparing properties against your family’s long-term criteria, negotiating on your behalf, and bringing in trusted notaires, tax advisers and renovation specialists once you are ready to structure the purchase for succession. Our search mandate service is built around exactly this kind of patient, well-governed search.
If you are weighing a Riviera property as a family legacy asset, get in touch for an initial conversation and we will talk through what a realistic search, timeline and structure could look like for you.
FAQ
What creates most of the world’s millionaires?
Real estate is widely cited by wealth researchers and financial commentators as one of the more common wealth-building vehicles, largely through long-term appreciation, leverage and debt pay-down rather than any single overnight gain. On the Riviera, that pattern tends to play out over decades and generations rather than single transactions.
What is the outlook for the French real estate market in 2026?
Recent notaires data for the Alpes-Maritimes shows transaction volumes have fallen from recent peaks while prices in many submarkets have held or risen modestly, according to the Chambre des notaires. INSEE’s regional data also points to a recovering new-build segment, with commercialisations up in 2025 even as the buyer mix shifts, so the picture looks like gradual stabilisation rather than sharp movement in either direction, as shown by INSEE’s regional conjoncture report.
What is the most expensive house on the French Riviera?
Published prices for individual trophy villas change frequently and are not consistently verified by a single authoritative source, so we would rather point you towards current listings and notaire data than quote a specific figure that may already be out of date. Exceptional villas in Cap d’Antibes, Saint-Jean-Cap-Ferrat and Saint-Tropez regularly set regional records, and a buyer agent can confirm current comparable sales for any specific property you are considering.
Is it wise to buy property in France now?
Whether now is the right moment depends far more on your own horizon and governance plans than on short-term market timing. Notaires data shows prices in parts of the Riviera have stayed resilient through a period of falling transaction volumes, which suggests a reasonably stable backdrop for buyers planning to hold for the long term, according to notaires’ analysis.
Sources
- Real Estate Generational Wealth Transfer: Planning Strategies for High Net Worth Families
- Insee — conjoncture Provence‑Alpes‑Côte d’Azur
- Immobilier sur la Côte d’Azur: les volumes ont atteint un plancher, les prix résistent encore
Recommended
 //